Earning rental income from residential flats, independent houses, or commercial shops is one of the most rewarding investment strategies in India. However, with the Income Tax Department's advanced automated data-matching tools—including the Annual Information Statement (AIS), Taxpayer Information Summary (TIS), and mandatory reporting of high-value banking transactions—unreported or miscalculated rental income is now one of the leading triggers for scrutiny notices under Section 148 of the Income Tax Act, 1961.
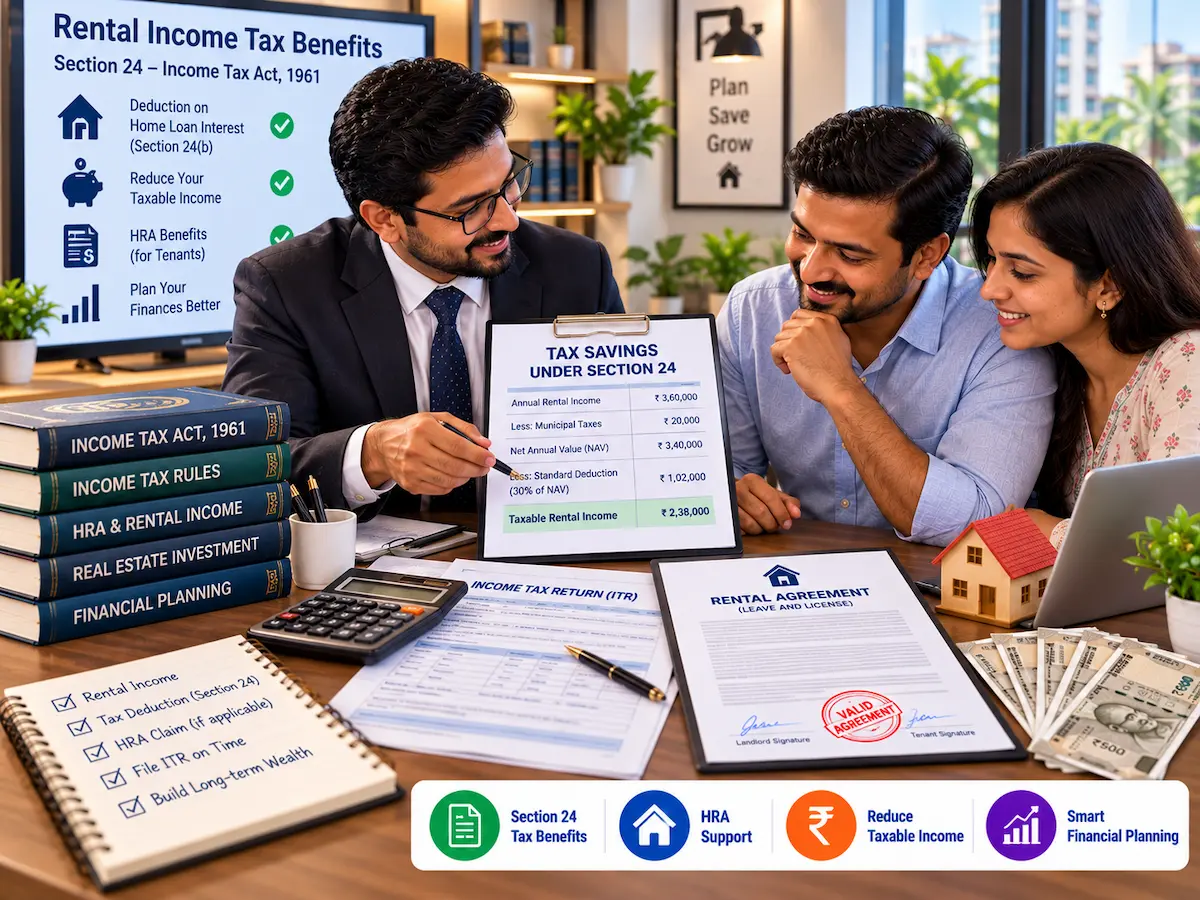
Many property owners mistakenly assume that their entire gross rental income is taxable at their personal slab rate. In reality, the Indian tax code provides powerful statutory tax shelters under Section 24—including a flat 30% Standard Deduction for repairs and maintenance regardless of actual spending, deductions for municipal property taxes paid, and substantial interest deductions on borrowed home loans. Furthermore, the interplay between the New Tax Regime (Section 115BAC) and the Old Tax Regime has fundamentally altered how house property losses can be set off against salary or business income.
Whether you are an individual homeowner letting out a 2BHK in Bangalore or Mumbai, a joint owner splitting rental yields with your spouse, or a corporate landlord managing commercial spaces, this comprehensive 2026 guide breaks down the computation of Income from House Property, Section 24 deductions, Section 194-IB TDS rules, and how executing a clear, structured rental agreement on LetOutAgree guarantees flawless tax compliance.
Draft a Tax-Ready Rental Agreement in 3 Minutes
Avoid tax notice hassles and TDS penalties. Generate an attorney-vetted rental agreement with structured rent breakdowns, explicit landlord PAN declarations, maintenance demarcations, and Section 24/194-IB compliance for flat ₹49.
How Rental Income Is Taxed in India: The 4-Step Computation
Rental income is classified and assessed under the statutory head "Income from House Property" (Sections 22 to 27 of the Income Tax Act). The calculation follows a strict statutory formula:
| Step | Component | Statutory Rule & Calculation |
|---|---|---|
| Step 1 | Gross Annual Value (GAV) | Higher of: (a) Reasonable Expected Rent (Municipal / Fair Rent) or (b) Actual Rent Received or Receivable during the financial year. |
| Step 2 | Less: Municipal Taxes Paid | Local municipal property taxes (BBMP, BMC, MCD, GCC, etc.) actually paid by the landlord during the financial year. (Taxes paid by the tenant or unpaid taxes cannot be deducted). |
| Step 3 | Net Annual Value (NAV) | NAV = GAV − Municipal Taxes Paid. This is the base upon which statutory deductions are applied. |
| Step 4 | Less: Deductions under Section 24 |
(a) Standard Deduction (Sec 24a): Flat 30% of NAV. (b) Home Loan Interest (Sec 24b): Actual interest paid on capital borrowed for purchase/construction. |
| Result | Taxable Income from House Property | NAV − 30% Standard Deduction − Home Loan Interest = Net Taxable Rent (taxed at your applicable slab rate). |
The Two Pillars of Section 24 Tax Deductions
1. Section 24(a): Flat 30% Standard Deduction
Under Section 24(a), every property owner letting out property is entitled to a statutory standard deduction of 30% of the Net Annual Value (NAV). This deduction is designed to cover routine property expenditures such as white-washing, painting, plumbing repairs, civil maintenance, lift charges, and rent collection expenses.
The beauty of Section 24(a) lies in its unconditional nature:
- No Proof or Invoices Required: You do not need to produce a single hardware bill, contractor receipt, or painting voucher to claim this 30% deduction.
- Available Even with Zero Expenditure: Even if you spent ₹0 on property maintenance during the year, you are still legally entitled to subtract 30% from the NAV.
- Cap on Deductions: Conversely, even if your actual renovation expenses exceeded 50% of the rent, your statutory deduction under Section 24(a) remains capped at exactly 30%.
2. Section 24(b): Home Loan Interest Deduction
If you purchased or constructed the rented house property using a bank home loan, the interest portion of your Equated Monthly Installments (EMI) provides substantial tax relief under Section 24(b):
- For Let-Out (Rented) Property: The entire actual interest paid during the financial year is deductible against the net rental income. Unlike self-occupied homes (where interest deduction is capped at ₹2,00,000 per year), there is no statutory ceiling on the interest you can claim against rental revenue from a let-out property.
- Pre-Construction Interest: Interest paid during the construction or pre-possession period of the property can be claimed in 5 equal annual installments starting from the financial year in which possession or completion certificate is obtained.
- Principal Repayment (Section 80C): Note that the principal repayment portion of your home loan is NOT deductible under Section 24; it falls under Section 80C (up to ₹1.5 Lakhs) and is only available under the Old Tax Regime.
New Tax Regime vs Old Tax Regime: Which Is Better for Landlords?
Following recent Union Budget amendments, the New Tax Regime (Section 115BAC) is the default tax regime in India. Understanding the differences between both regimes is critical for every property owner:
| Tax Benefit / Parameter | New Tax Regime (Sec 115BAC) | Old Tax Regime |
|---|---|---|
| Municipal Taxes Deduction | Allowed (Yes) | Allowed (Yes) |
| Sec 24(a) 30% Standard Deduction | Allowed (Yes) | Allowed (Yes) |
| Sec 24(b) Loan Interest on Let-Out Property | Allowed up to rental income (Cannot create net loss to set off against salary) | Full interest allowed |
| Set-off of House Property Loss against Salary | Not Allowed (₹0) | Allowed up to ₹2,00,000 per year |
| Carry Forward of Unabsorbed Loss | Allowed for 8 Assessment Years (Set off only against future house property income) | Allowed for 8 Assessment Years |
| Sec 80C Principal Repayment Deduction | Not Allowed | Allowed up to ₹1,50,000 |
Rule of Thumb: If you have a large home loan where annual interest significantly exceeds your net rental income, the Old Tax Regime may save you more tax because it lets you deduct up to ₹2,00,000 of property loss directly against your taxable salary. However, if your property is loan-free or has a modest loan balance, the lower slab rates of the New Tax Regime are almost universally more advantageous.
Live Tax Calculation Example: A Rented 2BHK Apartment
Let us examine a real-world scenario of a landlord in Chennai or Pune letting out a residential apartment:
- Monthly Rent: ₹30,000 (Annual Gross Rent = ₹3,60,000)
- Municipal Property Tax Paid: ₹12,000
- Home Loan Interest Paid: ₹1,50,000
| Calculation Step | Amount (₹) |
|---|---|
| Gross Annual Value (GAV) (₹30,000 × 12) | ₹3,60,000 |
| Less: Municipal Property Tax Paid | (−) ₹12,000 |
| Net Annual Value (NAV) | ₹3,48,000 |
| Less: 30% Standard Deduction under Section 24(a) (30% of ₹3,48,000) | (−) ₹1,04,400 |
| Less: Home Loan Interest under Section 24(b) | (−) ₹1,50,000 |
| Net Taxable Income from House Property | ₹93,600 |
Key Insight: Despite collecting ₹3,60,000 in gross annual rent, the landlord pays tax on only ₹93,600! Legitimate deductions sheltered nearly 74% of the rental income from tax.
TDS Rules on Rent: What Landlords & Tenants Must Know
The Income Tax Department enforces withholding tax provisions to track rental payments across India:
1. Section 194-IB: Individual & HUF Tenants
- Threshold: Applies when monthly rent exceeds ₹50,000 per month (or part of month).
- Rate: 5% TDS deducted once a year (in the last month of the tenancy financial year or upon vacating).
- No TAN Required: The tenant does not need a formal Tax Deduction Account Number (TAN). They simply file an online challan-cum-statement on the TIN-NSDL portal using Form 26QC and furnish Form 16C to the landlord within 15 days.
- No PAN Penalty: If the landlord fails to furnish their PAN, the TDS rate shoots up to 20% (capped at one month's rent).
2. Section 194-I: Companies, LLPs & Audited Firms
- Threshold: Applies if the total annual rent exceeds ₹2,40,000.
- Rate: 10% TDS on land, building, and furniture; 2% on machinery/equipment.
- Procedural Requirement: The corporate tenant must hold a valid TAN, deduct monthly TDS, file quarterly Form 26Q, and issue quarterly Form 16A certificates.
3. Section 195: Rent Paid to NRI Landlords
- If the property owner is a Non-Resident Indian (NRI), the domestic tenant must deduct TDS at the flat rate of 31.2% (30% + 4% Health & Education Cess) from the very first rupee of rent, unless the NRI landlord obtains a Nil or Lower Tax Deduction Certificate under Section 197 from the Income Tax Assessing Officer (see our Complete NRI Rental Agreement Guide).
Smart Tax-Saving Strategies for Property Owners
Strategy 1: Co-Ownership of Property (Section 26)
If you purchase a property jointly with your spouse or parent, the rental income is divided in proportion to each co-owner's defined share under Section 26. Each co-owner is entitled to:
- Their own basic tax exemption limit (up to ₹3 Lakhs under New Regime).
- A separate flat 30% Standard Deduction under Section 24(a).
- Individual home loan interest deductions under Section 24(b).
Splitting ₹60,000 monthly rent between husband and wife can bring both individuals into lower income tax slabs, potentially saving over ₹60,000 to ₹1,00,000 in annual taxes.
Strategy 2: Demarcate Maintenance Charges in the Agreement
When drafting your contract on LetOutAgree, always separate the Base Monthly Rent from the Society Maintenance Charges. If the tenant pays ₹25,000 as pure rent to you and ₹4,000 directly to the Resident Welfare Association (RWA) for maintenance, your Gross Annual Value is assessed on ₹25,000—preventing you from paying income tax on reimbursement sums you never retain as income.
Draft a Tax-Compliant Rental Agreement with LetOutAgree
A sloppy, informal rental agreement without explicit PAN declarations, rent due schedules, and maintenance demarcations exposes you to scrutiny notices and delays tenant HRA approvals. LetOutAgree makes generating an attorney-vetted agreement simple, compliant, and lightning-fast:
- Choose Your Property Format: Select Residential Rental Agreement or Commercial Shop Lease.
- Enter Verified Tax Particulars: Input Landlord PAN, Tenant PAN, monthly rent, and separate maintenance terms.
- Review Free Live Screen Preview: Check the complete deed on your screen before paying anything.
- Instant PDF Download for Flat ₹49: Pay securely via UPI or Card to immediately receive your print-ready A4 PDF calibrated for state e-Stamp paper attachment.
- HRA & Bank Approved: Hand the signed, e-stamped copy to your tenant for immediate HR payroll HRA submission and banking KYC.
This article is for informational purposes only and does not constitute legal advice. Please consult a qualified legal professional for advice specific to your situation.

Comments (0)
Login to leave a comment.