For millions of Non-Resident Indians (NRIs) living across the UAE, the United States, the United Kingdom, Singapore, Australia, and Canada, real estate in Indian metropolitan hubs—such as Bangalore, Mumbai, Chennai, Hyderabad, and Pune—remains one of the most lucrative asset classes. High rental yields, steady capital appreciation, and emotional ties to the motherland make Indian residential and commercial properties attractive long-term investments.
However, once your tenant begins depositing rent into your Indian bank account, an immediate logistical and regulatory challenge arises: How do you lawfully transfer those rental earnings out of India into your overseas bank account or convert them into freely repatriable foreign currency?
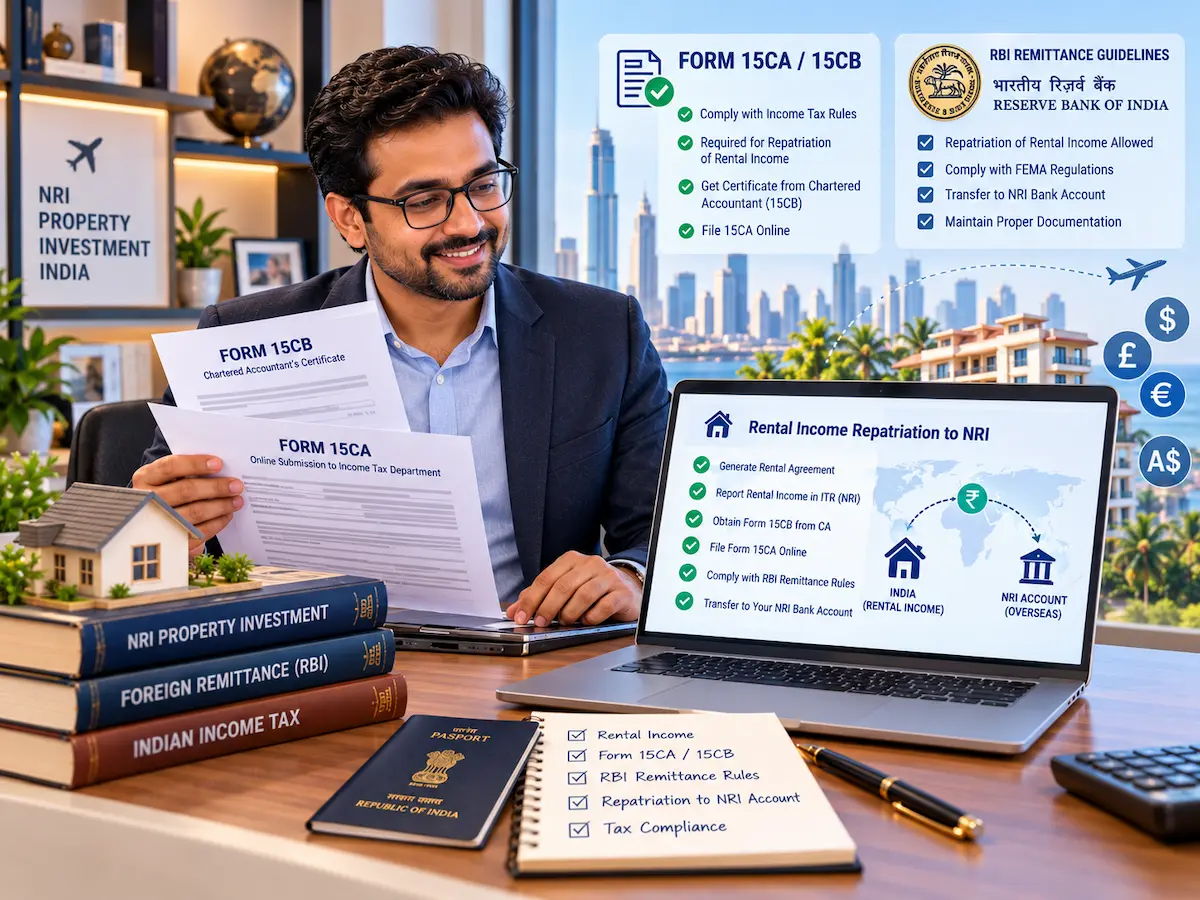
Under the statutory framework of the Foreign Exchange Management Act, 1999 (FEMA) and Reserve Bank of India (RBI) regulations, rental income earned in India cannot simply be wired abroad at the click of a standard net banking button. Because rental income is classified as domestic current income, it must first be deposited into a Non-Resident Ordinary (NRO) bank account. To repatriate these funds abroad or transfer them into a Non-Resident External (NRE) account, NRIs must complete statutory tax clearances governed by Form 15CA and Form 15CB under Section 195 of the Income Tax Act, 1961.
In this definitive 2026 guide, we unpack the RBI's USD 1 Million Remittance Scheme, break down the mandatory Form 15CA and Form 15CB filing steps, examine Double Tax Avoidance Agreements (DTAA), and explain why executing a legally airtight, registered rental agreement on LetOutAgree serves as your essential proof of the source of funds required by Indian banks and Chartered Accountants.
Draft an NRI-Compliant Rental Agreement in 3 Minutes
Ensure your Indian rental earnings are 100% repatriable. Generate an attorney-vetted agreement equipped with explicit NRO bank mandates, Section 195 TDS covenants, and formal landlord declarations for flat ₹49.

The Regulatory Framework: RBI's $1 Million Remittance Scheme
Under RBI Master Direction No. 13/2015-16 on Remittance of Assets, NRIs and Persons of Indian Origin (PIOs) are permitted to lawfully repatriate up to USD 1,000,000 (US Dollars One Million) per financial year (April 1 to March 31) out of balances held in their NRO accounts.
This statutory quota covers proceeds from:
- Current Income: Net rental income from immovable property, dividends, pension, and domestic bank interest.
- Capital Assets: Sale proceeds of ancestral or self-acquired residential/commercial property (subject to specific FEMA acquisition rules).
- Inheritance & Legacies: Monies received through registered wills or statutory succession decrees.
Crucial Rule: Because rental income represents "current account transactions" under Section 5 of FEMA, there is no statutory limit on repatriating legitimate net rental earnings, provided applicable Indian income taxes have been fully discharged and certified by an Indian Chartered Accountant.
NRO vs NRE Bank Accounts: Understanding the Flow of Rental Income
Many overseas property owners make the grave mistake of requesting their Indian tenant to wire monthly rent directly into their NRE account. Under FEMA regulations, depositing domestic Indian rupee earnings directly into an NRE account is illegal.
| Parameter | NRO Account (Non-Resident Ordinary) | NRE Account (Non-Resident External) |
|---|---|---|
| Purpose | To manage funds earned and accrued in India (Rent, Dividends, Pension). | To maintain foreign currency earnings converted into Indian Rupees. |
| Direct Deposit of Rent | Allowed & Mandatory | Strictly Prohibited by RBI / FEMA |
| Repatriability | Repatriable up to USD 1 Million/FY upon submitting Form 15CA/15CB. | Freely and fully repatriable anywhere in the world without limits or tax forms. |
| Interest Taxation in India | Taxable in India (Subject to 30% + cess TDS under Sec 195). | 100% Tax-Free in India under Section 10(4)(ii). |
The Legal Flow of Rental Funds:
- Tenant pays rent into your NRO Account (after deducting TDS under Section 195).
- You obtain Form 15CB (Chartered Accountant Certificate) and file Form 15CA (Online Tax Portal).
- Your bank transfers the cleared balance from your NRO Account → Overseas Foreign Account (or from NRO Account → NRE Account in India).
Demystifying Form 15CA and Form 15CB
To ensure that income leaving the country has not evaded Indian taxation, the Income Tax Department mandates a two-part digital certification process under Rule 37BB of the Income Tax Rules:
1. Form 15CB: The Chartered Accountant Certification
Form 15CB is an official statutory certificate issued and digitally signed by an independent practicing Chartered Accountant (CA) in India. The CA examines:
- The nature of the remittance (rental income vs asset sale).
- Verification of gross rent receipts against the NRI Rental Agreement.
- Verification that tenant deducted statutory 31.2% TDS under Section 195 (or that the landlord holds a valid Section 197 Lower Deduction Certificate).
- Payment of advance tax or self-assessment tax on any uncovered balance.
- Application of Double Tax Avoidance Agreement (DTAA) provisions if preferential rates were claimed.
- Generation of a unique UDIN (Unique Document Identification Number) by the CA via the ICAI portal to guarantee legal authenticity.
2. Form 15CA: The Remitter's Online Self-Declaration
Form 15CA is an online information undertaking furnished directly by the NRI remitter on the official Income Tax e-filing portal (eportal.incometax.gov.in). It contains 4 distinct parts:
| Part of Form 15CA | Applicability Threshold | Form 15CB Required? |
|---|---|---|
| Part A | Remittance is taxable and does NOT exceed ₹5,00,000 in aggregate during the financial year. | No (Self-declaration only) |
| Part B | Remittance exceeds ₹5,00,000 and a formal order/certificate has been obtained from the Assessing Officer under Sec 195(2), 195(3), or 197. | No (AO certificate details entered) |
| Part C | Remittance is taxable, exceeds ₹5,00,000 in the financial year, and NO AO order exists. (This is the most common route for NRI rental repatriation). | Yes (Mandatory CA Form 15CB + UDIN) |
| Part D | Remittance is NOT chargeable to tax under the Income Tax Act (e.g., specified exempt list under Rule 37BB). | No |
The 5-Step Step-by-Step Repatriation Process
Step 1: Document Gathering & Source of Funds Verification
Before contacting a Chartered Accountant or your Authorized Dealer (AD) Bank, compile your legal dossier:
- Executed & e-Stamped Rental Agreement: Proves the contractual source of domestic income. Must reflect tenant name, rent amount, and property address matching your bank records.
- NRO Bank Account Statements: Demonstrating credit entries for monthly rent received.
- TDS Certificates (Form 16A): Issued by the tenant proving deduction and deposit of withholding tax under Section 195 into the central government treasury.
- Property Ownership Proof: Registered Sale Deed, Mother Deed, or latest Municipal Property Tax receipt in your name.
- Valid Passports & NRI Visas: Proving your non-resident immigration status under FEMA.
Step 2: CA Review & Issuance of Form 15CB
Your Indian Chartered Accountant verifies the numbers:
- The CA calculates your Gross Rental Value, subtracts local property taxes paid, allows the Section 24(a) 30% Standard Deduction, and computes net tax liability.
- The CA cross-checks taxes deposited against your Form 26AS and Annual Information Statement (AIS).
- The CA uploads Form 15CB directly onto the Income Tax e-filing portal using their CA digital signature certificate (DSC) and generates the mandatory UDIN.
Step 3: Filing Form 15CA (Part C) on the Tax Portal
Once the CA submits Form 15CB, it appears in your personal Income Tax portal dashboard:
- Log into incometax.gov.in using your Indian PAN.
- Navigate to e-File → Income Tax Forms → File Income Tax Forms → Form 15CA.
- Select Part C. Link the CA's Form 15CB acknowledgment number and UDIN.
- Input the Authorized Dealer Bank details (Bank Name, Branch, IFSC / SWIFT code, and BSR code).
- Submit and verify the form via Aadhaar OTP, Net Banking, or Digital Signature (DSC). Download the final generated Form 15CA Acknowledgment Receipt.
Step 4: Submitting Form A2 & Repatriation Pack to Your Bank
Submit the complete repatriation docket to your Indian bank's Forex / NRI Services branch (ICICI, HDFC, SBI, Axis, Kotak, etc.):
- Form A2: RBI's standard application-cum-declaration for purchase of foreign exchange.
- FEMA Declaration: Stating that total remittances from all sources do not exceed USD 1,000,000 for the ongoing financial year.
- Signed Copy of Form 15CA and Form 15CB.
- Underlying Proof: Copy of your Rental Agreement and latest bank statements.
Step 5: Fund Transfer (NRO to Foreign Bank or NRO to NRE)
Upon satisfactory document scrutiny, the bank executes the transaction:
- Option A (Direct Foreign Remittance): The bank converts INR at the day's card exchange rate and executes an outward Telegraphic Transfer (TT) directly into your overseas checking account in Dubai, London, New York, or Toronto (typically takes 24 to 48 hours).
- Option B (NRO to NRE Transfer): The bank debits your NRO account and credits your tax-exempt NRE savings account in Indian Rupees. Once inside your NRE account, the funds become 100% freely repatriable at any future date without needing new 15CA/15CB filings!
Double Tax Avoidance Agreement (DTAA) & Foreign Tax Credits
Does paying Indian taxes mean you get taxed again in your country of residence? No. India has entered into comprehensive Double Tax Avoidance Agreements (DTAA) with over 85 countries, including the USA, UK, UAE, Canada, Germany, Singapore, and Australia.
- Immovable Property Rule: Under almost all DTAA conventions (Article 6), income from immovable property is primarily taxable in the country where the property is physically situated (India).
- Claiming Foreign Tax Credit (FTC): When filing your annual tax return in your resident country (e.g., IRS Form 1040 in the US or Self Assessment in the UK), you report your Indian rental income and claim a dollar-for-dollar Foreign Tax Credit (IRS Form 1116 in the US / Foreign Tax Credit Relief in the UK) for the taxes paid to the Indian government.
- Zero Tax Jurisdictions (UAE / GCC): For NRIs residing in Dubai, Abu Dhabi, or Qatar where personal income tax is zero, Indian taxes paid under Section 195/24 represent the complete and final tax settlement on those earnings.
Why an Airtight Rental Agreement Is Mandatory for Repatriation
Authorized Dealer banks in India are subject to strict Reserve Bank of India audits under anti-money laundering (AML) and FEMA compliance mandates. If your rental agreement is vague, hand-scrawled, improperly stamped, or signed on expired dates, the bank's foreign exchange desk will freeze or reject your repatriation request.
By drafting your contract on LetOutAgree, you equip yourself with an institution-grade legal document:
- Explicit Bank Account Mandate: Details your specific NRO bank account, branch, and IFSC code for clean audit trails.
- Section 195 TDS Compliance Clause: Explicitly binds the tenant to deposit statutory withholding tax and furnish Form 16A TDS certificates quarterly.
- State-Specific e-Stamp Paper Compliant: Calibrated for immediate attachment to state e-Stamp certificates, satisfying bank legal validation criteria.
- Live Free Screen Preview & Instant ₹49 Download: Inspect every clause on screen and download your high-resolution A4 print PDF in less than 3 minutes.
This article is for informational purposes only and does not constitute legal advice. Please consult a qualified legal professional for advice specific to your situation.
Comments (0)
Login to leave a comment.